Let's Find Opportunities Overseas
Tag: Institutional Ownership

⚡ Nebius (NBIS): $140M Insider Selling Meets 454% AI Revenue Growth
Nebius Group (NBIS) delivered extraordinary 454% revenue growth to $582 million in Q2 2026—but reported insider sales approaching $140 million, $5.66 billion in quarterly capital expenditures, and a 49% share-price decline complicate the investment thesis. Is this AI infrastructure powerhouse becoming a bargain, or is the market pricing in bigger risks? FunStock Index™: 6.66/10.

🔌 Magnachip ( MX): Deep-Value Bargain or Ultimate Value Trap? CEO Buys $318K as Navitas Bets $5M ⚡
Magnachip has spent 15 years destroying shareholder value. Now its new CEO is buying 100,000 shares, Navitas is investing $5 million, and a silicon-carbide pivot is taking shape. Deep-value bargain—or another chapter in the value trap?

🛵 Grab Holdings (GRAB): CEO Buys $30M at $2.89 as a $900M Buyback & $1.5B Atome Deal Reshape the Story 🍔📱
Grab CEO Anthony Tan just committed nearly $30 million of personal capital to GRAB at $2.89—and COO Alexander Hungate joined him. Add a planned $900 million buyback, 54% Q2 adjusted EBITDA growth, $5.4 billion of net cash liquidity and a $1.49 billion Atome acquisition, and Southeast Asia's superapp may be entering a very different chapter. The opportunity looks compelling. The execution risks haven't disappeared.

🚛 Waste Connections (WCN): Trading Trash for Pure Cash
Waste Connections (WCN) may operate in garbage, but its business model is pure gold. After a 23% pullback from all-time highs, founder-CEO Ronald Mittelstaedt just bought $7.6 million worth of shares in the open market. With elite margins, recession-resistant cash flow, institutional dominance, and almost zero short sellers, WCN looks less like a trash company and more like a compounding machine disguised as a dump truck.

NVCR Stock Analysis 2026: Is Novocure’s Pancreatic Cancer Breakthrough a Buy?
Novocure is trying to fight cancer with electric fields, not pills — and its new FDA approval in pancreatic cancer may be the catalyst that changes everything. NVCR remains speculative, but with heavy institutional backing, improving fundamentals, and a beaten-down stock price, the risk/reward is getting harder to ignore.
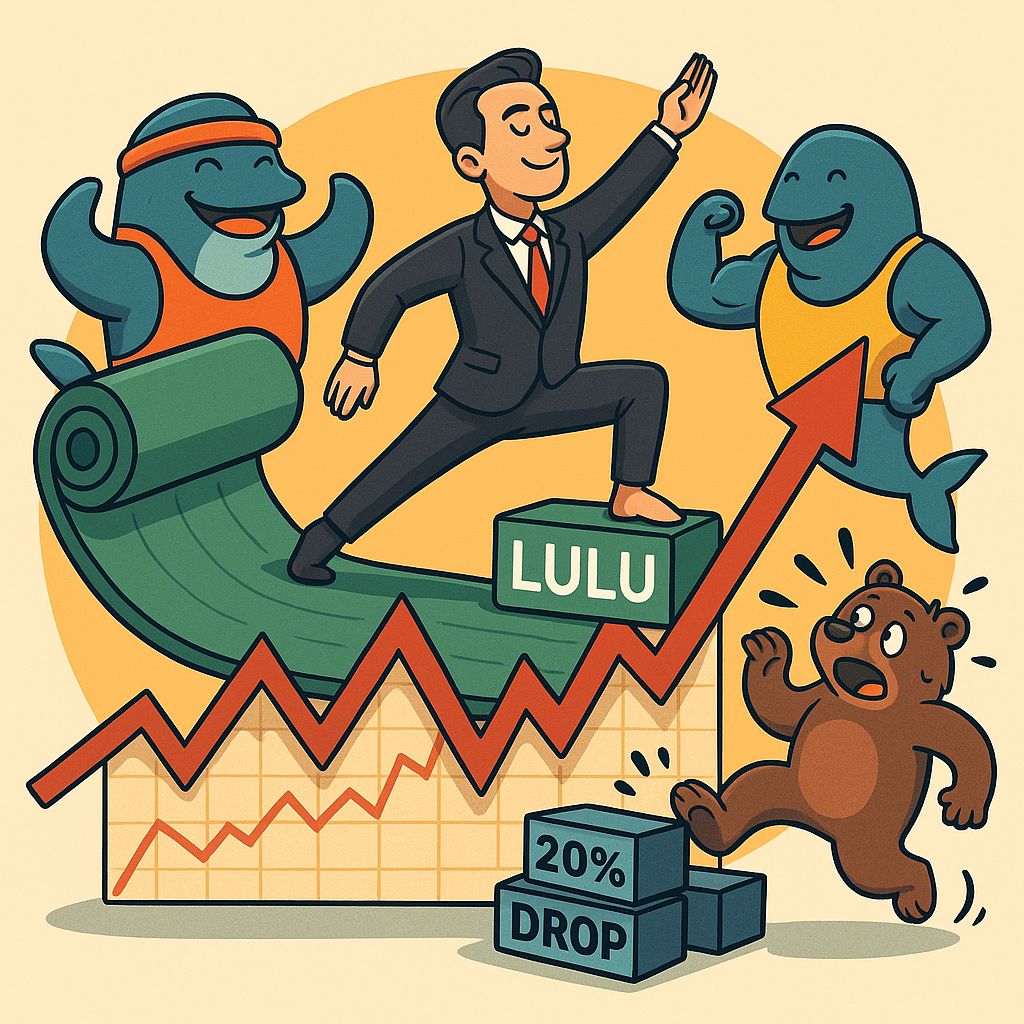
Lululemon: Don’t Sweat the Small Stuff
Lululemon shares just faceplanted—down 20%—but insiders (and leggings lovers) may see a bounce coming. From CEO buys to global growth and cult-level brand loyalty, here’s why LULU might be worth the stretch. 🧘💰